
-
 19.11.2026UAE Publishes Updated Guidance on Tax Groups
-
 17.11.2026K.A.C. Group Partners Participated in TAX & BUSINESS TALKS 2026 — A2B FORUM on November 13
-
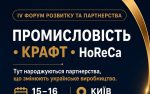 27.10.2026K.A.C. Group Partner Tetiana Yanovska Took Part in the 4th INDUSTRY • CRAFT • HoReCa Forum
-
 22.10.2026OECD Publishes 2026 CbC Reporting Peer Review Compilation
-
 19.10.2026EU Updates List of Non-cooperative Jurisdictions for Tax Purposes
UAE Publishes Updated Guidance on Tax Groups
published: 19.11.2026
The UAE Federal Tax Authority issued an updated version of the Corporate Tax Guide on Tax Groups ‒ CTGTGR1 (November 2026), which replaces the first version issued in January 2024.
Definition and Characteristics of a Tax Group
A Tax Group as two or more taxable persons treated as a single taxable person according to the conditions of Article 40 of the Corporate Tax Law. Only resident persons can be part of a Tax Group.
A Parent Company and one or more Subsidiaries can make an application to the FTA to form a Tax Group where all of the following conditions in Article 40(1) of the Corporate Tax Law are met:
• The Parent Company and each Subsidiary are juridical persons;
• The Parent Company and each Subsidiary are Resident Persons;
• The Parent Company owns at least 95% of the share capital of each Subsidiary, either directly or indirectly through one or more Subsidiaries;
• The Parent Company holds at least 95% of the voting rights of each Subsidiary, either directly or indirectly through one or more Subsidiaries;
• The Parent Company is entitled to at least 95% of each Subsidiary’s profits and net assets, either directly or indirectly through one or more Subsidiaries;
• Neither the Parent Company nor the Subsidiaries are an Exempt Person;
• Neither the Parent Company nor the Subsidiaries are a Qualifying Free Zone Person;
• The Parent Company and each Subsidiary have the same financial year;
• The Parent Company and each Subsidiary prepare their financial statements using the same accounting standards.
Responsibilities of the Parent Company of a Tax Group
• The Parent Company and the relevant Subsidiary should jointly apply to the FTA, if a new Subsidiary wishes to join an existing Tax Group.
• The Parent Company shall prepare aggregated financial statements of the Tax Group.
• The Parent Company shall file a tax return on behalf of the Tax Group no later than 9 months from the end of the relevant tax period, or by such other date as directed by the FTA.
• The Parent Company must settle the corporate tax payable on behalf of the Tax Group within 9 months from the end of the relevant tax period, or by such other date as determined by the FTA.
• The Parent Company may apply for a corporate tax refund on behalf of the Tax Group, if the relevant conditions are met.
• The Parent Company must register and deregister the Tax Group.
• The Parent Company is responsible for maintaining sufficient and adequate supporting documents related to the financial records, transfer pricing documentation, and submitting any clarification request to the FTA.
Taxation Treatment of a Tax Group
A Tax Group is treated as a single Taxable Person for the purposes of the Corporate Tax Law, so the Tax Group has one Taxable Income, which is reported by the Parent Company. The aggregated financial statements of the Tax Group shall be audited by a special purpose audit. Taxable income subject to the 0% corporate tax rate shall be limited up to AED 375,000,217 (USD 102,110,338) regardless of the number of entities that are included in the Tax Group.
The freshest
Categories
- Media (93)
- News (225)
- Events (38)
- Ukrainian Historical Notaphily (4)

