
-
 14.10.2026Draft Law Approved to Implement EU Rules on Limiting Corporate Borrowing Costs in Ukraine
-
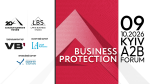 12.10.2026K.A.C. Group Took Part in BUSINESS PROTECTION 2026 – A2B FORUM on October 9
-
 06.10.2026UAE Publishes Updated Guidance on Free Zones and Designated Zones for Tax Purposes
-
 09.09.2026OECD Publishes Tax Policy Reforms Report for 2025
-
 31.08.2026Ireland Publishes Updated Guidance on Crypto-Asset Reporting
Draft Law Approved to Implement EU Rules on Limiting Corporate Borrowing Costs in Ukraine
published: 14.10.2026
On October 13, the Cabinet of Ministers approved in principle Draft Law No. 16036 dated September 4, 2026, developed by the Ministry of Finance, to amend the Tax Code of Ukraine in order to implement Article 4 of Council Directive (EU) 2016/1164 (the Anti-Tax Avoidance Directive, ATAD) and OECD BEPS Action 4 regarding the prevention of base erosion.
The new measure is based on Article 4 of ATAD: the deduction of interest on corporate debt obligations will henceforth be subject to a specific limit on borrowing costs for tax purposes. This limit will be calculated as the sum of interest income (and income economically equivalent to interest) plus the greater of two values: 30% of EBITDA (earnings before interest, taxes, depreciation, and amortization) or a monetary threshold of EUR 500,000 (EUR 3 million for certain categories of loans from unrelated parties). Consequently, companies will be unable to artificially inflate loan-related expenses to reduce their tax liability in Ukraine.
The rule will apply to all debt obligations of corporate income taxpayers, regardless of the lender’s country of residence. Accumulated and unrecognized borrowing costs may be carried forward to subsequent tax periods without time limits, while the unused portion of the limit may be carried forward to the next five tax years.
The new rules will apply starting January 1, 2028; the current provisions of the Tax Code of Ukraine will apply to the reporting period preceding this date.
The Ministry of Finance also proposes introducing other mechanisms, absent during the screening of Ukrainian legislation for EU compliance but planned for future implementation:
1) Exit tax (Art. 5 of ATAD): If a corporate income taxpayer transfers assets to its permanent establishment abroad, relocates the operations of a non-resident’s permanent establishment outside Ukraine, changes tax residence, or undergoes “tax migration,” the capital gain on such assets is subject to taxation in Ukraine.
The following are not considered relocations: change in the physical location of an asset without Ukraine losing its taxing rights; temporary relocations of up to 12 months related to securities transactions, collateral, prudential capital requirements, or liquidity management; and the transfer of assets and funds between a taxpayer and its subsidiary.
2) General Anti-Abuse Rule (GAAR): Concepts such as “tax abuse,” “tax benefit,” “series of transactions,” and “indicators of an artificial transaction” are introduced. If a transaction formally complies with the law but is artificial and executed solely for a tax benefi, contrary to the underlying purpose of the legal provision, its tax consequences will be neutralized. A taxpayer is not entitled to a tax benefit if the entitlement arose from a transaction constituting tax abuse.
A specific business purpose test (Art. 3 of ATAD) is introduced for all transactions involving corporate income tax payers, requiring an adjustment to the financial result for transactions lacking a business purpose.
3) Hybrids (Arts. 9, 9a–9b of ATAD): Situations may arise where a single financial instrument, transaction, or entity is treated differently across two jurisdictions, resulting in a double deduction of expenses or a deduction without a corresponding inclusion of income. In Ukraine, such discrepancies can be resolved in two ways: by denying the expense deduction or by including the income.
4) Control measures: Establishment of a standing commission on GAAR application within the State Tax Service; introduction of new grounds for unscheduled documentary audits without prior delivery of the audit order; extension of the period for determining tax liabilities and retaining documents related to such audits from 1095 to 2555 days; registration and reporting in Ukraine of foreign companies managed from Ukraine.
The freshest
Categories
- Media (93)
- News (222)
- Events (36)
- Ukrainian Historical Notaphily (4)

